Market Overview: Defining the Skin Care Stores Market Landscape
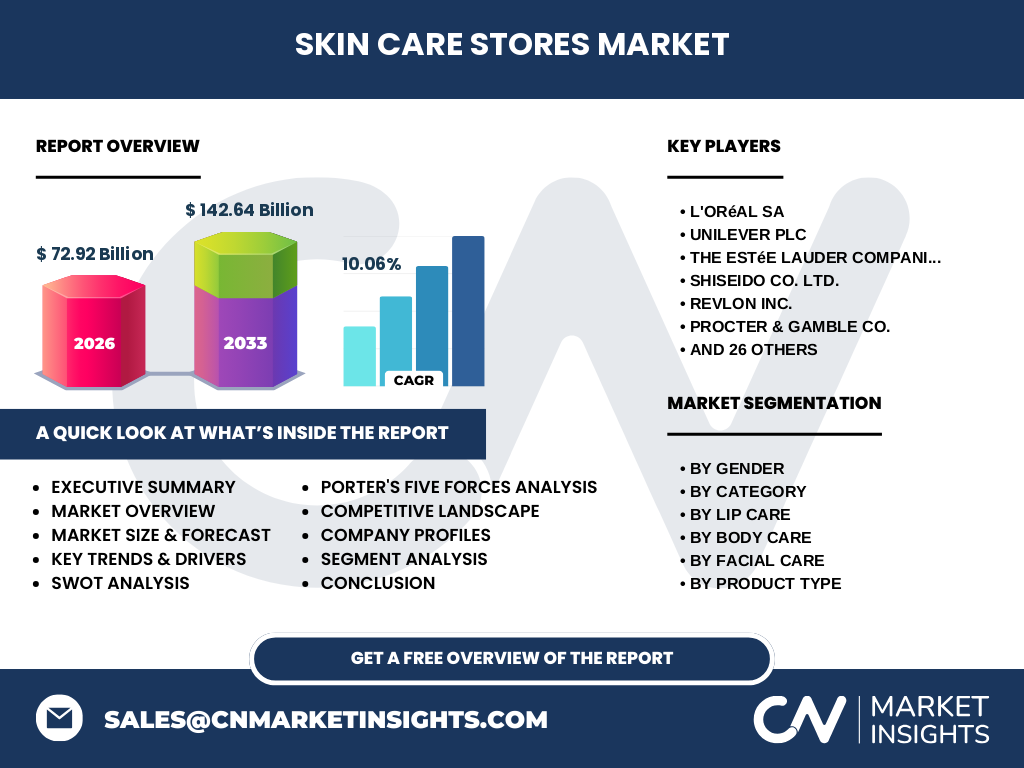
The Skin Care Stores Market encompasses specialized retail environments—from high-end boutiques to omnichannel pharmacy counters—facilitating the distribution of advanced dermatological and cosmetic solutions. Valued at 72.92 Billion in 2026, the industry serves as a critical nexus between R&D innovators like L'Oréal SA and end-consumers. The scope includes facial, body, and lip care, operating under stringent regulatory frameworks managed by bodies such as the FDA and EU Cosmetics Regulation.
Structural Growth Drivers and Market Constraints
Primary growth is fueled by rising consumer demand for dermatologically-tested formulations and clean-label ingredients. However, the industry faces logistical hurdles in cold-chain distribution for bio-active serums and supply chain volatility for specialized raw materials. The Estée Lauder Companies Inc. and Shiseido Co. Ltd. are navigating these constraints by localizing supply chains, while the opportunity lies in scaling personalized digital diagnostic tools to capture the 10.06% CAGR projected through 2033.
The Shift Toward Niche Skincare and E-commerce
The market is witnessing a profound 'skin-tellectual' movement, where consumers prioritize scientific efficacy over branding. This trend shifts power toward specialized brands like Drunk Elephant LLC and Deciem Beauty Group Inc., which leverage direct-to-consumer online stores. These players disrupt traditional retail by offering transparency in ingredient sourcing, compelling supermarkets and hypermarkets to curate more premium, clinical-grade facial care products to remain competitive.
COVID-19 Impact and Resilience Trajectory
The pandemic initially disrupted physical storefronts, causing a temporary slump in traditional pharmacy and mall-based retail. However, the Skin Care Stores Market displayed remarkable resilience by pivoting toward hygiene-centric and self-care products. The recovery trajectory, evidenced by the current 72.92 Billion valuation, highlights a permanent shift where robust online stores now act as a primary interface, effectively bridging the gap for consumers during periods of restricted mobility.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high, dominated by conglomerates like Procter & Gamble Co., Unilever plc, and Kao Corporation. These giants leverage massive distribution networks and global manufacturing footprints. Meanwhile, agile disruptors like Glossier Inc. and Tatcha LLC challenge established norms via community-driven marketing. Strategic dynamics now center on M&A activity, as conglomerates acquire boutique, science-backed labs to stay relevant in a fast-evolving, trend-sensitive environment.
Executive Summary of the Skin Care Stores Market Outlook
Our research identifies the Skin Care Stores Market as a high-growth sector set to expand from 72.92 Billion in 2026 to 142.64 Billion by 2033. This growth, at a 10.06% CAGR, is underpinned by rapid adoption of facial care regimens and the proliferation of accessible, omnichannel retail. Stakeholders must prioritize digital transformation and supply chain agility to navigate the complex regulatory landscapes across global markets.
Projected Market Forecast 2027-2033
The forecast for the Skin Care Stores Market indicates a steady rise, reaching an estimated 142.64 Billion by 2033. This expansion is driven by aging populations seeking anti-aging serums and a surge in male grooming demand. Market participants will benefit from increasing penetration in emerging economies, provided they navigate regional taxation and import regulations effectively to maintain the projected 10.06% CAGR.
Segmentation Analysis: Deep Dive into Product and Distribution Roles
The market segments, including Facial Care, Lip Care, and Body Care, serve distinct roles. Facial care (cleansers, masks, serums) remains the highest-value category. Distribution channels like pharmacy and online stores are critical for growth, providing the necessary credibility and convenience required by modern shoppers. We segment by gender and category to help firms like Clarins Group and Murad LLC refine their target-marketing strategies across diverse demographics.
Regional Performance and Geographic Distribution
Geographic performance reveals that North America and Europe currently hold significant market share due to high disposable income and well-established premium skin care products retail infrastructure. However, Asia-Pacific is accelerating rapidly due to increasing urbanization and a growing middle class. Companies like Amorepacific Corporation demonstrate how regional expertise in innovative formulations can capture local market demand better than standardized global strategies.
In-Depth Regional Review of Key Markets
In North America, Ulta Beauty Inc. thrives by integrating luxury and mass-market products. Conversely, the Asian market requires navigating stringent localized safety standards for ingredients like lightening agents. In Europe, Beiersdorf AG and LVMH Moët Hennessy Louis Vuitton SE lead by emphasizing sustainability and ethical sourcing, aligning with the regulatory priorities of the European Chemicals Agency, which shapes consumer sentiment and, ultimately, store-level inventory selection.
Strategic Positioning of Leading Companies
Leading companies adopt distinct strategies: Johnson & Johnson Services Inc. and Colgate-Palmolive Company focus on mass skin care products, leveraging economies of scale. Meanwhile, Babor Cosmetics America Corp. and Dermalogica Inc. occupy the professional-grade tier, using skincare professionals to drive brand loyalty. This spectrum ensures that whether in supermarkets or exclusive boutiques, the market effectively captures both necessity and luxury-oriented consumer spending.
Porter’s Five Forces Analysis of the Skin Care Industry
Our analysis reveals high competitive rivalry among established players like Revlon Inc. and Coty Inc., driving aggressive R&D spending. Threat of new entrants is mitigated by high regulatory hurdles and brand loyalty, though digital-first brands often bypass these barriers. Buyer power is significant in the mass-market segment, while professional brands maintain higher margins through exclusive distribution agreements and strong medical endorsement, reducing price sensitivity.
SWOT Analysis: Strategic Evaluation
Strengths: Strong brand equity for giants like Natura & Co.. Weaknesses: High dependency on raw material imports. Opportunities: Rapid growth in male grooming and eco-friendly packaging using bottles and tubes made from recycled content. Threats: Evolving regulatory landscapes globally, specifically concerning ingredient safety protocols and packaging sustainability mandates, which may force firms like Avon Products Inc. to redesign their supply chains and product architectures.
Value Chain Analysis: From Raw Materials to End-Users
The value chain begins with high-grade active ingredients, proceeding through formulation by companies like Mary Kay Inc. or Oriflame Cosmetics AG. Packaging solutions—specifically jars, tubes, and bottles—are critical for shelf-life protection. Logistics flows through major ports like Rotterdam or Long Beach, reaching online stores or physical retailers, where the final value is extracted via direct consumer interaction and personalized advisory services.
Investment Insights and Strategic Recommendations
Investors should focus on firms integrating AI-driven skin analysis at the point of sale. The 10.06% CAGR suggests a robust upside. We recommend targeting clean-label manufacturers and brands with strong online stores infrastructure, as these segments are outperforming traditional retail. Partnerships with Nu Skin Enterprises Inc. or Rodan & Fields LLC may offer high-potential entry points due to their unique direct-sales and community-based distribution models.
Conclusion and Key Takeaways
The Skin Care Stores Market is evolving into a technology-enabled, highly segmented ecosystem. With the industry projected to reach 142.64 Billion by 2033, the primary success factors remain product differentiation, omnichannel agility, and adherence to shifting regulatory standards. Companies that harmonize scientific credibility with seamless digital experiences, as seen with modern innovators, are best positioned to lead this rapid market expansion.
Research Methodology: How We Triangulate Data
Our baseline estimates are derived from a triangulation model. We synthesize trade registry data, audit public financial filings from companies like L'Oréal SA, and conduct primary stakeholder interviews with retail managers. This quantitative framework is balanced against macroeconomic indicators such as consumer price indices and regional spending power to ensure the validity of our 10.06% CAGR and subsequent market size forecasts.
Scope of the Report and Coverage Parameters
This report covers the global Skin Care Stores Market, focusing on facial care, lip care, and body care segments. We analyze performance across key retail channels, including supermarkets, pharmacy, and online stores. Limitations include focus on commercial retail; professional-only medical skin treatments performed strictly in clinics are excluded to maintain the focus on consumer-accessible retail environments.
Recent Developments: Shaping the Future of Skincare Retail
Recent announcements show Mario Badescu Skin Care Inc. and Kate Somerville Skincare LLC expanding into international pharmacy networks to boost visibility. Major players like Procter & Gamble Co. have prioritized sustainability-focused partnerships to reduce plastic waste in jars and tubes. These strategic moves illustrate a sector-wide commitment to balancing aggressive growth with corporate social responsibility, ensuring long-term viability in a highly discerning, environmentally conscious consumer market.